Market overview and structural scope of the Interceptor Missiles Market
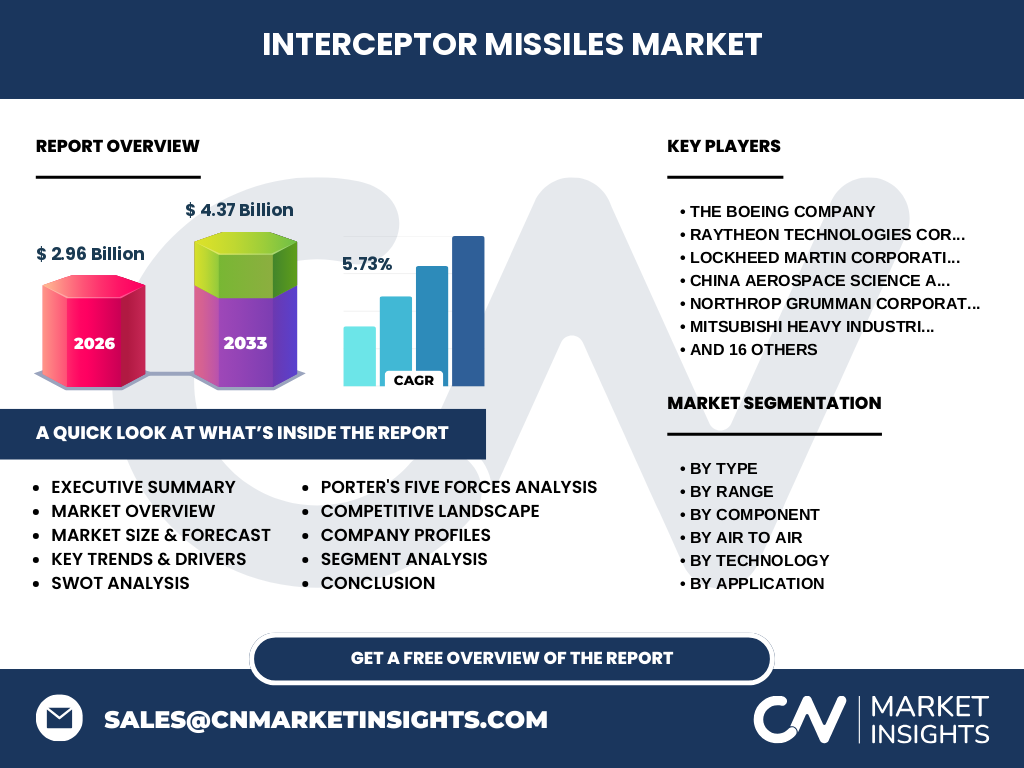
Our analysis indicates that the Interceptor Missiles Market is valued at $2.96 Billion in 2026, serving as a critical pillar of global aerospace and defense architecture. This market encompasses advanced defensive munitions designed to intercept and neutralize incoming aerial threats, including hypersonic glide vehicles and tactical ballistic systems, governed by strict defense export controls.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical friction and modernization initiatives across major military powers. However, protracted supply chain bottlenecks for specialized raw materials like carbon-carbon composites and stringent regulatory compliance enforced by bodies such as the US Department of State under ITAR act as significant operational restraints.
Emerging Technological Trends in the Interceptor Missiles Market
Industry trends highlight a decisive shift toward directed-energy integration and artificial intelligence-enabled guidance systems. Major innovators are heavily investing in advanced seeker technologies, specifically upgrading Infrared and Radar Homing capabilities to counter highly maneuverable electronic countermeasures deployed in modern contested airspace.
Evaluating the COVID-19 Impact on Defense Supply Chains
The pandemic severely disrupted Tier-2 and Tier-3 component suppliers, causing temporary delays in complex sub-assemblies for the Interceptor Missiles Market. Recovery has been accelerated by multi-year government funding injections, allowing primes like Lockheed Martin Corporation and Raytheon Technologies Corporation to fortify domestic manufacturing redundancies.
Competitive Benchmarking and Strategic Dynamics
Market concentration is notably high, dominated by established prime contractors who leverage deep technological moats. Companies such as MBDA, Northrop Grumman Corporation, and Israel Aerospace Industries Ltd. maintain competitive dominance through strategic vertical integration and long-term joint development contracts with sovereign defense ministries.
Executive Summary of the Interceptor Missiles Market Industry Trends
Our comprehensive research projects the Interceptor Missiles Market to expand from $2.96 Billion in 2026 to $4.37 Billion by 2033, registering a robust 5.73% CAGR. Demand is heavily anchored by multi-layered air defense deployments across the Asia-Pacific and European theaters.
Market Forecast and Long-Term Trajectory Through 2033
Driven by sustained procurement cycles and rising defense budgets globally, the market trajectory displays consistent upward momentum. Reaching $4.37 Billion by 2033 at a 5.73% CAGR, growth will be primarily sustained by rising investments in naval vertical launch systems and advanced regional defense shields.
Segmentation Analysis by Type, Range, and Component
The sector segments across Surface-To-Air, Air-To-Air, and Water-To-Air types, spanning Short, Medium, and Long-Range operational parameters. Component integration—ranging from Global Positioning System and Inertial Navigation System to advanced seeker heads—dictates the precision and cost profile of each defensive asset.
Regional Market Performance and Geographic Distribution
Geographic performance is led by North America and the Asia-Pacific region, where localized security challenges mandate continuous capability upgrades. European markets are concurrently expanding indigenous production capacities, driven by collaborative European defense initiatives involving firms like Diehl Defence GmbH & Co. KG and Saab AB.
In-Depth Regional Review of High-Growth Defense Corridors
The Asia-Pacific corridor demonstrates exceptional demand elasticity due to territorial disputes and accelerated naval fleet modernizations. Meanwhile, Middle Eastern markets prioritize localized integration of advanced systems like Iron Dome and Patriot-GEM-T, bolstered by strategic technology-sharing partnerships with international defense contractors.
Company Profiles and Strategic Positioning
Industry leaders like The Boeing Company, China Aerospace Science and Technology Corporation, and Mitsubishi Heavy Industries Ltd. position themselves through specialized R&D in hypersonic defense. European counterparts such as Thales Group and Kongsberg Defence & Aerospace AS focus on interoperable command-and-control software architecture.
Porter's Five Forces Analysis of the Interceptor Missiles Market
Bargaining power of buyers is exceptionally high given that sovereign governments are the sole purchasers. Conversely, threat of new entrants remains extremely low due to prohibitive capital expenditure requirements, stringent defense accreditation processes, and proprietary intellectual property protections surrounding radar homing and propulsion.
SWOT Analysis of the Interceptor Missiles Market Industry
Key strengths include unmatched technological sophistication and vital national security relevance. Weaknesses involve vulnerable supply chains for rare earth elements. Opportunities lie in joint export markets, while major threats stem from disruptive asymmetrical warfare tactics and escalating cyber vulnerabilities in guidance networks.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying titanium alloys and energetic materials, flowing through specialized component manufacturers building Semi-Active Lasers and radar arrays. System integrators then deliver finished interceptors to military end-users via highly secure logistics channels.
Investment Insights and High-Potential Strategic Areas
Investors should target early-stage innovators specializing in miniaturized sensor payloads and resilient communications links. Companies capable of integrating software-defined upgrades into legacy missile platforms present superior risk-adjusted return profiles within the broader Interceptor Missiles Market.
Conclusion and Key Takeaways for Market Stakeholders
With the market set to scale from $2.96 Billion in 2026 to $4.37 Billion by 2033 at a 5.73% CAGR, stakeholders must prioritize R&D agility. Success depends on aligning product portfolios with next-generation threat profiles, particularly hypersonic and multi-domain aerial attacks.
Research Methodology and Baseline Triangulation
Our findings are derived by triangulating primary stakeholder interviews with senior defense procurement officials, official trade registry filings, and secondary macroeconomic indicators. Quantitative models cross-reference historical budget allocations with announced defense modernization contracts to ensure high statistical fidelity.
Scope of the Report and Analytical Boundaries
This report covers global deployment trends, technological categorizations, and competitive profiling within the Interceptor Missiles Market from 2026 through 2033. Exclusions apply to classified black-budget research programs and offensive ballistic missile development initiatives outside defined defensive parameters.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features strategic joint ventures between firms like Rafael Advanced Defense Systems Ltd. and international primes to co-develop counter-drone and counter-missile solutions. Furthermore, increased contract awards for advanced variants like the Standard Missile-3 underscore sustained institutional commitment to robust missile defense shields.